A 15-Day, Expert-Led Turnaround in the Highest-Risk Step of the Loan
How a $8.5B+ national mortgage lender replaced its high-cost legacy outsourcing model with OwnGCC’s highly experienced underwriters reaching full independence in just 15 days, lifting daily production 33%, cutting FTE cost 17%, and halving conditioning errors without a single line of process re-engineering.
DAYS TO FULL
INDEPENDENCE
PRODUCTION GAIN
LOWER FTE COST
FEWER CONDITIONING
ERRORS
Net effect: a 67% cut in training time on top, expert underwriters productive after just two walkthroughs and fully independent within 15 days.
1
Executive Summary
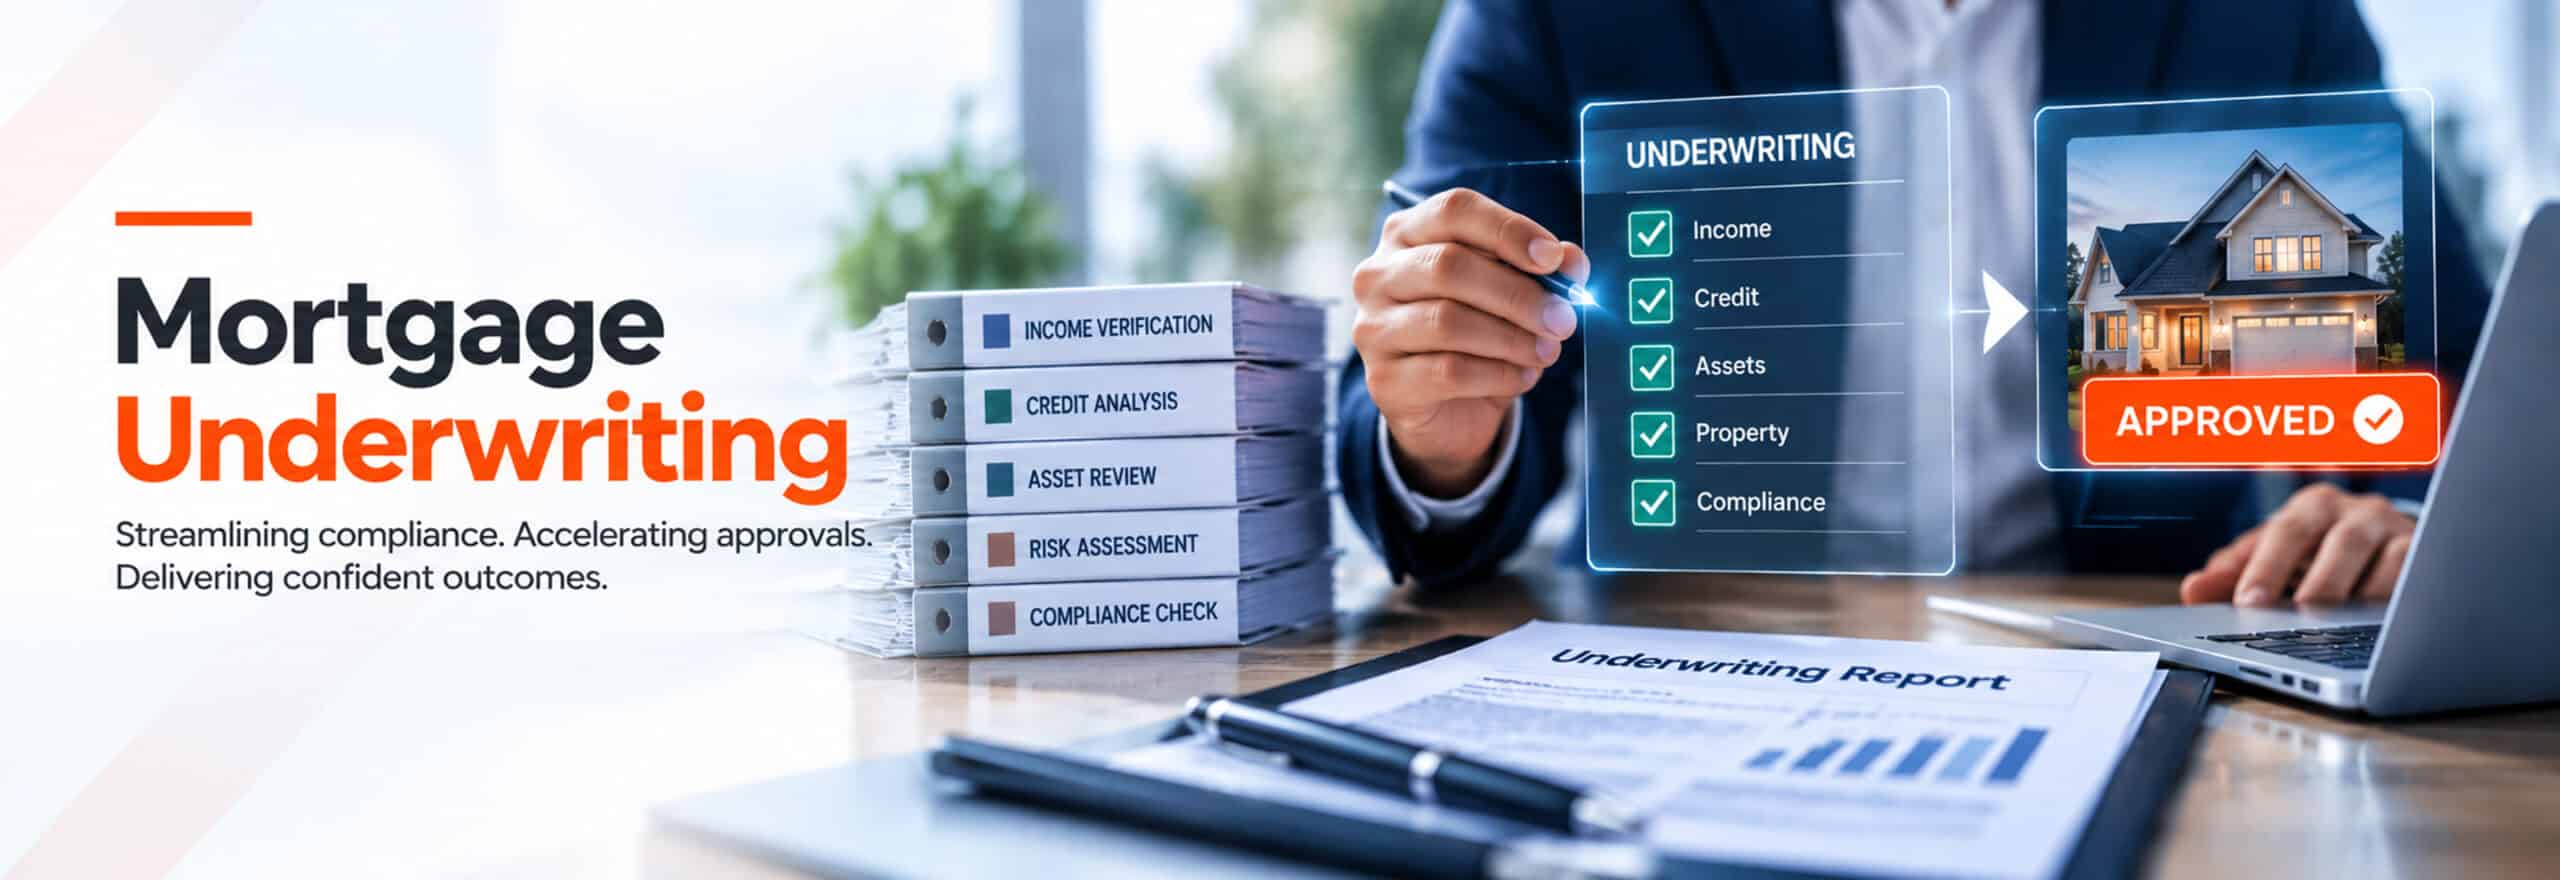
In residential mortgage lending, underwriting is where credit risk, regulatory exposure, and speed to close all collide. Every file that sits idle in an underwriting queue extends time-to-close, threatens rate locks, and increases the lender’s exposure to investor pushback and repurchase risk. For one prominent national lender, a legacy outsourcing arrangement had turned this critical function into a liability — inflated FTE pricing, stacked underwriting queues, and recurring condition and guideline-application errors were compressing margins and eroding investor confidence.
After seven years with a traditional BPO, the lender sought a more agile underwriting partner. By replacing that provider with OwnGCC and its highly experienced underwriting talent, the lender started to see the turnaround in just 15 days — with only two process walkthroughs, no intensive retraining, and no disruptive workflow redesign. The talent-led model delivered a 33% increase in daily production, a 17% reduction in FTE cost, a 50% reduction in conditioning errors, and a 67% cut in training time — two weeks versus the legacy six. Convinced by results they could measure in the first two weeks, executive leadership authorized expansion of the scale of engagement in Underwriting as well as into additional departments like Disclosure & Closing.
2
Client Profile & Operational Challenge
The client is a fast-growing national mortgage lender on track to fund more than $8.5B in mortgages in 2026 across retail, wholesale, and correspondent channels. Issuing timely, defensible underwriting decisions is essential to keeping the pipeline moving without slipping closing dates or forcing costly rate-lock extensions.
Under its legacy vendor, four bottlenecks had become chronic:
Layered, Over-Priced FTE Model.
Premium per-underwriter rates padded with supervisor/QA layers while the actual underwriters were low paid causing frequent attrition.
Long Ramp, Low Output.
6 weeks to train plus shadowing, productivity of 3 files/day even though the scope only required initial underwriter (no conditions or CTC as in the scope)
Recurring Conditioning Errors.
Over/under-conditioning and QM/ATR misapplication, while the feedback was acknowledged no noticeable change in performance.
No Time to Train From Scratch.
No motivation to go through long transition period as they had invested significant amount of time and effort with the current relationship and it was hard to trust someone new.
3
Strategic Implementation
Rather than a lengthy training and transition including workflow redesign, the strategy centred on human-capital excellence and domain mastery. OwnGCC placed elite underwriting specialists directly into the existing workflow to drive immediate operational stability, value delivered through people, not overhead.
Domain-Expert Deployment
Seasoned underwriters — fluent in Fannie Mae DU, Freddie Mac LP, FHA/VA/USDA overlays, QM/ATR rules, and investor guidelines owned credit decisioning end to end after just two walkthroughs, reaching full independence within 15 days.
Scalable Team Expansion
Every efficiency, quality, and cost benchmark was met within the first month, prompting the client to formally approve additional underwriting headcount to support pipeline growth.
4
Measurable Results
Deploying senior domain talent produced immediate, quantifiable gains across every key operational metric:
| Metric Area | Legacy Vendor Model | OwnGCC Model | Net Operational Impact |
|---|---|---|---|
| Training | 6 weeks | 2 weeks | 67% faster |
| Daily Production | 3 files per underwriter per day | 4 files per underwriter per day (on average) | 33% production gain |
| FTE Cost | High legacy FTE rate | 17% lower FTE cost | 17% direct margin gain |
| Transition to Independence | Months of shadowing & ramp-up | 2 walkthroughs, fully live in 15 days | Fully autonomous in 15 days |
| Conditioning Accuracy | Recurring conditioning errors | 50% fewer conditioning errors | Halved rework & repurchase risk |
5
Conclusion & Forward Outlook
In just 15 days — after only two walkthroughs — a high-volume national lender moved from a costly, error-prone outsourcing model to an agile, accurate, cost-efficient underwriting operation: 33% more daily production, 17% lower FTE cost, 50% fewer conditioning errors, and 67% less training time. The proof of expert human capital was unmistakable, and it earned OwnGCC formal approval to grow the team and extend the partnership across new functions. The same playbook is ready to scale wherever speed, precision, and margin matter most.